
You've been out to the site and the client is asking for a price that day. Sure, you can give them a ballpark. But if you don't have any basis for that number, you won't know how to adjust for rising prices or quantities. Details like site access, removal of existing material, or conditions behind a wall can make a difference to the bottom line.
The following interior construction examples break down the price. These are just calculations to make the point, not market prices. Use your measurements, current supplier prices, labor rates and local requirements.
Project scope and site assumptions
List the project address, client, version of the drawing or specification, work area and expected result. Break down the work into demolition, prep work, installation, finishing and cleanup. Consider site access, utilities, hours of work, existing conditions, storage, protection and client decisions still to be made.
For the first example, we're assuming 30 square meters of flooring. The client has confirmed the material type, and the site is ready to proceed. Make sure to check individually whether demolition, subfloor repair, moving materials and disposal are included. If you don't know, treat it as unresolved; don't assume it's OK.
Area is not necessarily the amount to buy. Take into account layout and materials and method of work to estimate cutting waste. Don't use a standard waste % for all projects.
- Address, document version
- Work phases and deliverables
- Site access and site-condition assumptions
- Client-provided information or decisions
Worked construction estimate example
Document the basis of quantities and costs so you can recalculate if the client changes the scope.
The first example does not include tax, retention or advance payments. Installation labor is 24 hours × 120 yuan/hour = 2,880 yuan. Purchased flooring materials are 33 square meters × 80 yuan/square meter = 2,640 yuan. Consumables estimated from the item list are 480 yuan. Transport and disposal estimated from the site arrangements are 600 yuan. The total direct cost is 6,600 yuan.
In another flooring project example, this one in dollars and imperial units, the work area is 240 square feet. The four cost items below add up to $3,800. Add the fixture allowance of $600 and permit allowance of $250 to get $4,650 before applicable tax. This is a different project, not a currency conversion of the first.
- Demolition and disposal | 16 labor hours × $65/hour | $1,040
- Subfloor material | 12 sheets × $45/sheet | $540
- Flooring installation | 240 square feet × $8/square foot | $1,920
- Equipment rental | 2 days × $150/day | $300
- Line-item total $3,800 + fixture allowance $600 + permit allowance $250 = $4,650 before applicable tax
The estimate sent to the client should have the address, drawing or scope version, material specifications, access conditions, expected time frame, what's not included, change-order rules and how each allowance will be reconciled.
Put in verified site quantities, vendor prices, labor rates and local requirements in place of the examples.
Allowances, overhead, and total
Back to our yuan project example: 600 yuan of allocated overhead brings the total cost to 7,200 yuan. A markup on cost of 20% gives a selling price of 8,640 yuan, with a difference of 1,440 yuan. Using this example's cost basis, the difference as a share of the selling price is 1,440 ÷ 8,640, approximately 16.67%, not 20%. Markup uses cost as the denominator; margin uses the selling price.
If selections or quantities are not settled, include an allowance. Describe what is included and how actual cost impacts price. If using contingency, describe the identified uncertainties and explain it according to the pricing method and agreement. Do not include it as an unexplained extra charge. Do not conceal known work or count a cost twice.
The agreed project structure should include permits, disposal, delivery, overhead, profit, discounts and applicable taxes. Check that your subtotals and percentages make sense and that the estimated total matches. Make sure your price covers operating costs and risk and provides a reasonable return. If you make no profit in a month of work, what could you have missed? Do not just tack on some random number.
- Clearly indicated allowances
- Permits, delivery and disposal
- How overhead and profit are handled
- Subtotal, taxes and estimated total
Schedule, exclusions, and changes
Be aware of subfloor conditions, hidden pipes and work restrictions that may change costs. Explain what you know, any provisional items and how changes will be confirmed. Share the estimate validity, expected start window, duration, payment milestones and change process together.
Describe how permits, material delivery, inspections, weather and customer selections impact the schedule. Don't commit to a completion date without considering these dependencies. Clearly define exclusions. Price and schedule additional work and get written approval as agreed before proceeding, except where the governing agreement provides a lawful emergency process. For more complex projects, develop a more detailed list based on the contract and applicable requirements.
- Expected start window and duration
- Permit/material dependencies
- Specific exclusions
- Written change-order process
Start with the site, not the spreadsheet
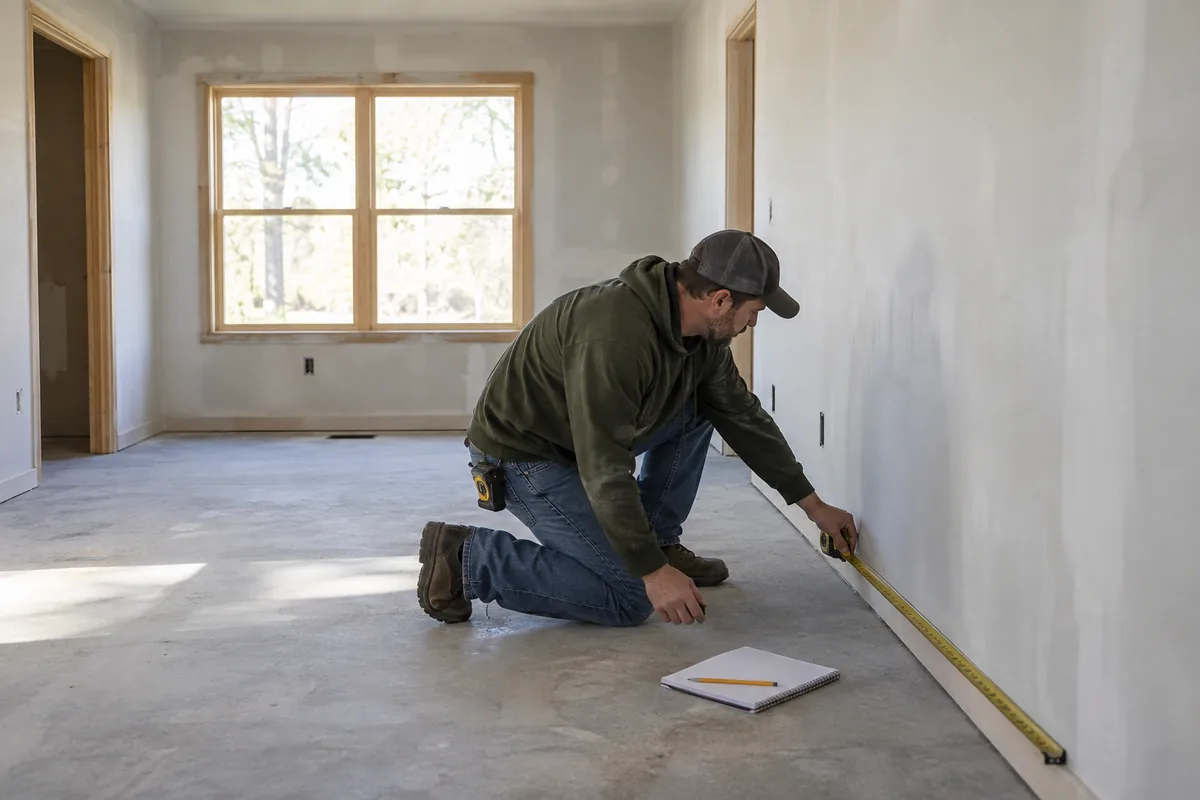
Site notes aren't just dimensions. Surface repairs, how materials can be brought onto the site, working-time restrictions, protection of existing equipment and waste disposal all affect labor and other costs. Capture these conditions and the desired finish so you don't need to rely on memory later when estimating.
Relevant photos obtained appropriately are useful for later reference. Preferably include a location and description. For example, with a wall photo, will it be obvious a few days later which room it is in? For concealed areas, record what you've checked and what remains unknown. Work out a review process with the client, then decide on a fixed quote or a conditional estimate.
Build quantities and material costs separately
Be careful with the quantity needed for the work versus the purchase quantity. Materials might come in boxes, rolls or sheets. Cutting, overlaps and site waste may increase what you need to buy. Estimate waste based on the material and method. Don't use a generic percentage for all jobs.
For each measurement, include quantity, unit, supplier price and the basis for waste or packaging quantities. Are delivery and other charges included? How long is the supplier quote valid? Does it include tax? When was the important material pricing information obtained?
Some items are priced “per pack” but cover different areas. Get the quantities into the same units to compare purchase options. If the selection is not settled, specify an allowance and explain the effect of an alternative on the price. Don't give the impression that a provisional allowance is a guaranteed fixed material cost.
Account for the labor around the main task
Don't forget about labor for things other than the main task: masking, protection, moving materials, demolition, tool setup, construction, cleanup and any necessary return visits. If you're just considering the main construction task, actual time can come out higher than your estimate. Break labor hours down by task, then factor in crew size to estimate elapsed project time.
For example, a day each for two people is two people's labor, but the job might still take only one day. Two people each working 4 hours produce 8 labor-hours, while the actual elapsed time on site might be only 4 hours. Don't confuse labor-hours and elapsed time. Work out the selling price based on the agreed individual or crew rate.
For specialist subcontracting, make sure you're clear on scope, price and site access, and keep labor assumptions that can be checked.
Do not confuse markup with margin
8,000 yuan is the full cost. A 25% markup results in a pre-tax price of 10,000 yuan and a difference of 2,000 yuan. This difference is 20% of the price you're selling at. So a 25% markup is not a 25% margin. You need to know the right way to calculate your target margin.
If overhead, rework or other costs have been left out, the difference on paper may not be your final profit. List costs as fully as possible, without counting the same charge in both overhead and contingency, then use a clear pricing method. Just increasing a percentage doesn't make clear where the costs are coming from. Apply tax and other adjustments according to the actual transaction.
| Illustrative calculation | Amount |
|---|---|
| Estimated cost | 8,000 yuan |
| 25% markup on cost | 2,000 yuan |
| Pre-tax selling price | 10,000 yuan |
| Difference as a share of selling price | 20% |
Present a base scope and meaningful options
Provide the client with a base scope and price. Then present the options as separate elements.
If the client's budget is tight, compare material specifications, finishes, phased work and optional extras that could be omitted. What is the scope? What is the cost? What are the schedule implications of the different options? What's mandatory and what's optional? Don't quietly cut safety measures, code requirements or necessary procedures to lower the price.
If circumstances change after your site visit, communicate the new scope and price before proceeding with additional work, where practical. Document the client's approval and accepted version, and follow the written-change and emergency procedures described above.
You may not need the same percentage drop in price just because the area drops. Your transport, preparation and equipment costs might not decrease in the same ratio. Recalculate from the actual costs.
Compare the estimate with the completed job
Once finished, compare estimated and actual quantities, materials, labor and other costs. Did differences come from measurement, scope changes, supplier increases, productivity, site conditions or missed preparation time? Write down the reasons to give your next estimate a concrete basis.
Keep the already accepted commercial agreement for this project. Internal cost changes do not automatically alter a fixed-price agreement.
Questions you may still have
How detailed should a construction estimate be?
It depends on the size and risk of the project, the client's needs and applicable requirements. At a minimum, connect scope, quantities, assumptions and price.
What is an allowance in a construction estimate?
It's a provisional amount for a selection or quantity that is not yet determined. Mention what the allowance is for and how actual cost affects the price.
Should contingency be shown to the client?
Explain contingency based on the pricing method and agreement. It should reflect identified uncertainties, without becoming an unexplained cost, covering up known work or duplicating costs.